

Review Your Rate and Repayments
Compare the rate you pay today with suitable alternatives. Look at fees and the remaining loan term alongside any potential repayment reduction.
A Fresh Look at Your Loan.
A Clearer Way Forward.
Has your home loan kept up with your life? Compare your current loan with suitable options from our 30+ lender panel and understand what a change could mean for you.
Your circumstances change. Your loan may need to change with them.
Compare the rate you pay today with suitable alternatives. Look at fees and the remaining loan term alongside any potential repayment reduction.
Explore offset accounts, extra repayments or a different fixed and variable structure. Compare feature costs with the value they offer you.
Discuss renovations, an investment purchase or debt consolidation. We explain what a lender will need to assess before you commit.
Look beyond the headline rate
A refinance review starts with your existing loan and what you want to achieve. We look at the full picture, including whether asking your current lender for a better deal makes sense.
Review My Home Loan →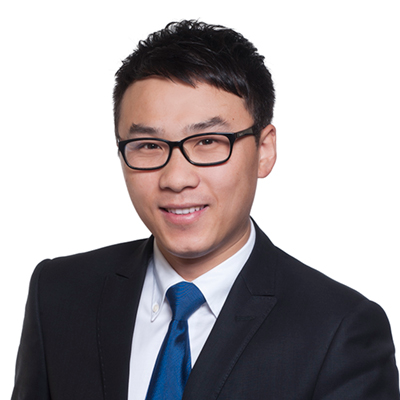
Lester Li · Mortgage Broker
With over a decade of experience in mortgage broking and a solid academic foundation in Applied Finance, Accounting, and Risk Management, I am dedicated to helping individuals, families, and business owners achieve their financial goals through smart lending solutions.
My expertise lies in structuring complex loan scenarios, including self-employed lending, investment finance, debt consolidation, construction lending, and strategic borrowing solutions. I work closely with my clients to understand their unique circumstances and develop tailored finance strategies that deliver real results.
I believe that exceptional customer service starts with listening. By taking the time to understand your needs and providing honest, transparent advice, I aim to make every finance journey simple, stress-free, and rewarding.
At LeMerit Finance, you can expect professional guidance, clear communication, and a trusted partner who is committed to supporting you every step of the way.
Get to Know Lester →Tell Lester about your current mortgage, circumstances and what you want to change.
Review suitable loans, features and switching costs, including staying with your lender where appropriate.
If you choose to proceed, we help organise the documents and submit the application to the chosen lender.
Following approval, we help with the discharge and settlement steps and explain your new loan arrangements.
Know the costs first
Refinancing has costs. We help identify the charges that apply to your existing and proposed loans so you can weigh them against any benefit.
Request current figures from your lender before making a decision. Costs and eligibility vary by lender and loan.
Understand the Loan Process and Fees →Check discharge fees and, for fixed-rate loans, any break cost.
Check application, valuation, settlement and government mortgage registration charges where applicable.
If your equity is below 20%, lenders mortgage insurance may apply. Include it in the comparison.
Extending the term may reduce repayments but increase total interest. Compare similar terms first.
Put the numbers in context
For example, if switching costs $1,500 and the monthly saving is $100, a simple break-even calculation is 15 months. That assumes the saving stays the same and excludes other changes.
Check the total cost as well as the monthly repayment, especially if you extend the term or add debts to the loan.
Try the Home Loan Calculator →Illustrative example only. No rate or saving is promised. Calculator results are estimates, not a loan offer.A considered decision
A fixed-rate break cost, a small loan balance or a short remaining term can change the result. If switching does not add up, you can explore a rate review with your current lender.
You do not need to decide before the conversation. Start by understanding your options.
Local knowledge. National support.
Based at 1 Valma St, Bayswater, LeMerit Finance supports homeowners in Ringwood, Rowville, Boronia, Lilydale, Burwood, Vermont, Glen Waverley, Wantirna, Wantirna South and Croydon, as well as clients across Melbourne and Australia.
Talk About Your Refinancing Plans →Home loan refinancing FAQs
Have a question about your existing mortgage? Call Lester →
Refinancing replaces your existing home loan with a new loan. You might move to another lender or discuss a different loan with your current lender. The review should consider your goals, remaining term, features and total costs.
You can ask your existing lender to review your rate. We can compare that response with suitable alternatives from our panel, so you can decide whether switching is worthwhile.
Costs depend on your current loan and the proposed new loan. Ask for a full cost breakdown before proceeding, including any fixed-rate break cost, discharge fee and new loan or mortgage registration charges.
It may be possible, depending on the lender and your circumstances. Lenders mortgage insurance may apply and could outweigh potential savings. A property valuation and lending assessment are required.
You can discuss borrowing against available equity for an acceptable purpose, such as renovations. Available equity is not an automatic borrowing entitlement: the lender still assesses your income, expenses, debts and property.
Some lenders allow eligible debt consolidation. Extending short-term debt over a mortgage term can increase total interest, even when the monthly repayment falls. Moving unsecured debts into your mortgage also puts your home at risk if you cannot repay.
You may be able to, but breaking a fixed-rate period can involve a significant cost. Ask your lender for a current payout and break-cost quote before comparing the options.
A formal loan application generally involves a credit enquiry. Your credit history forms part of the lender’s assessment. Discuss your position before submitting applications to several lenders.
Timing varies with the lender, documents, valuation and discharge process. Lester can explain the likely steps for your application and help coordinate them; approval and settlement dates cannot be guaranteed.
Start with identification, recent home loan statements, income evidence and details of your expenses and other debts. Self-Employed Applicants may need business financial records. Lester will confirm the documents required for the lender and your circumstances.
Yes, you can discuss both with Lester. Lenders assess investment and self-employed income differently, so the available options depend on your records, commitments, property and lending criteria.
Start with a home loan review
Tell Lester what you would like to change. We will contact you to discuss your current home loan and possible next steps.
General information only. Loan approval, rates and features depend on lender criteria and your circumstances. Consider the full costs before refinancing. Read ASIC Moneysmart’s guide to switching home loans ↗.